Your Next Investment Property Could Come With a Tax Advantage. Here’s What to Know Before Year-End.
By the Andy Bovender Team at Compass | September 14, 2026
An investment property can catch your eye with beautiful design and a location you love. Before making an offer, though, it pays to understand how the purchase fits your tax picture. Bonus depreciation may improve an investment property's early cash flow by accelerating certain deductions, but the benefit depends on the assets you buy, when they become available for rental use, and your ability to use the resulting loss.
What 100 percent bonus depreciation actually covers
Current federal law provides 100% bonus depreciation for qualifying property acquired and placed in service after January 19, 2025. The provision has no scheduled expiration under current law. For a calendar-year taxpayer targeting a 2026 deduction, December 31, 2026 matters because it ends the tax year, not because the 100% allowance disappears. Acquisition rules, including certain binding-contract rules, still require CPA review. IRS Notice 2026-11
The entire home purchase price does not qualify for an immediate write-off. Land is not depreciable, and the building generally follows a longer depreciation schedule. Residential rental buildings typically use 27.5 years under the general depreciation system; your CPA should confirm the classification for your intended use. Eligible shorter-lived assets may include appliances, furniture, and certain land improvements. Qualifying used assets can also be eligible, subject to acquisition requirements. IRS Publication 946
A properly supported cost segregation study can identify components with shorter recovery periods, often 5, 7, or 15 years, and allocate eligible costs separately from the building. It does not make every renovation or amenity bonus-eligible, and there is no universal percentage of a home's price that qualifies. IRS cost segregation guide
For illustration only, if a CPA identifies $100,000 of eligible basis and the full deduction offsets income taxed at 35%, the simplified federal tax reduction would be $35,000. That is a deduction from taxable income, not a $100,000 tax credit. This example is not an estimate for 904 Randall Drive and excludes other limitations and tax effects.
Closing and placing a property in service are different milestones
Closing transfers ownership. Placing a rental property in service generally means it is ready and available for its intended rental use. Those dates can match, but they often do not. The first guest does not necessarily need to arrive before year-end if the property is genuinely ready and available to rent. IRS Publication 527
Consider a buyer who closes December 18 but finishes necessary repairs and makes the home available for rental on January 10. That ordinarily points to a January placed-in-service date. A home genuinely ready and offered for rental December 20 could have a December date even if its first guest arrives in January. An online advertisement alone cannot establish readiness for a home that cannot yet host guests.
Build time into the purchase for required rental approvals, insurance, repairs, utilities, furnishings, and management setup. Keep dated evidence of readiness and availability for your CPA. A later tax-return filing deadline does not extend the property's year-end placed-in-service deadline.
A deduction only helps now if you can use it now
Rental losses are generally passive, so a large depreciation deduction does not automatically offset salary or business income. Unused losses may carry forward. Some short-term rental activities fall outside the tax definition of a rental activity, including when average customer use is seven days or less, but material participation and other limitations still matter. A short-term rental listing alone does not establish eligibility to offset other income. IRS Publication 925
Personal stays and family use can also limit rental deductions. Accelerating depreciation reduces the basis remaining for future deductions, and a later sale can trigger depreciation recapture. Ask your CPA to model the ownership period and eventual sale, as well as the first year's return. IRS rental-use rules and sale guidance; IRS Publication 544
Questions to bring to your CPA before making an offer
• Which assets qualify, how should land and building value be allocated, and would a cost segregation study justify its cost?
• What can you actually deduct this year after passive-loss, basis, at-risk, and excess-business-loss limits?
• How do your rental strategy, average guest stay, personal use, and management arrangement affect the result? What participation records should you keep?
• What evidence establishes the placed-in-service date, and which asset purchases need separate documentation?
• How will South Carolina and your home state treat the federal deduction? Would electing out of bonus depreciation make sense?
• What happens if you later sell, stop renting, or convert the property into a personal home?
A property to consider in Old Mount Pleasant
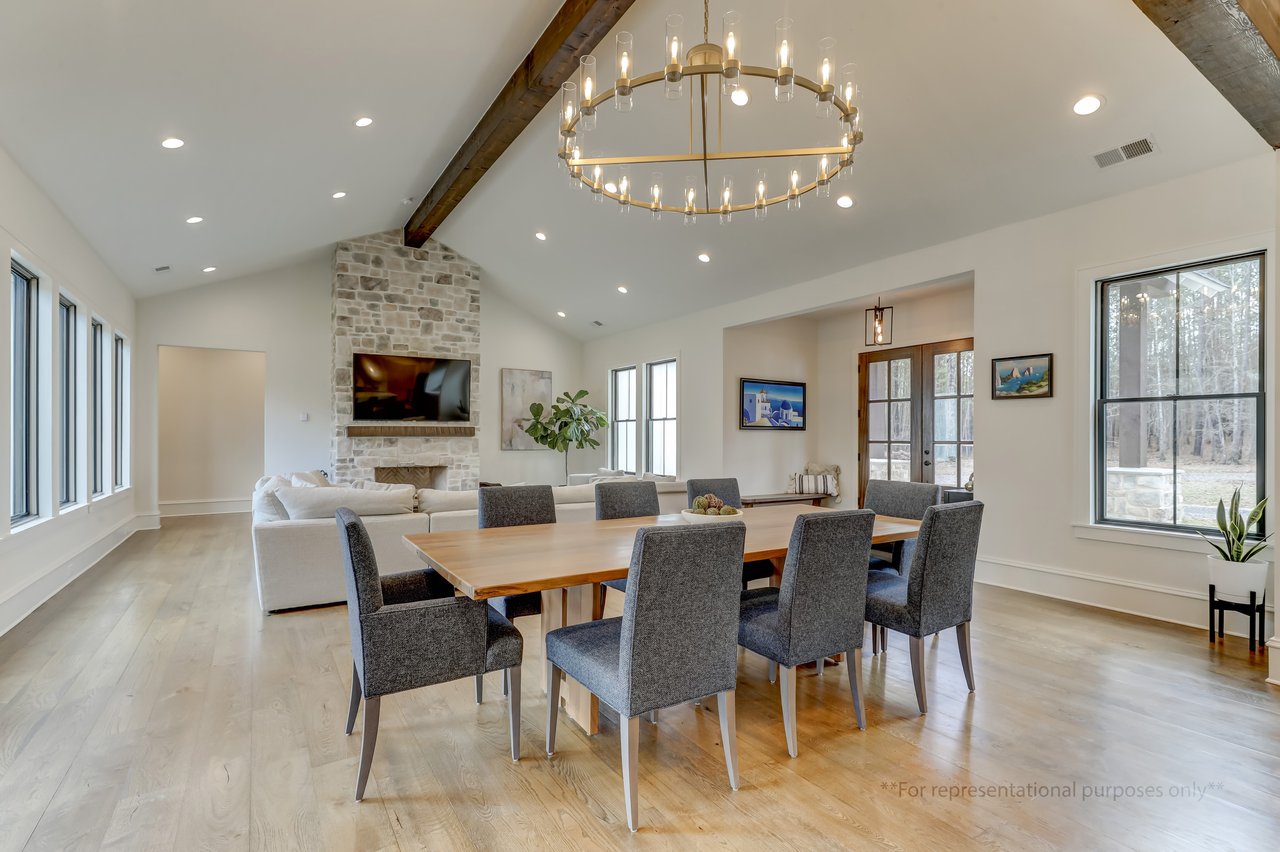
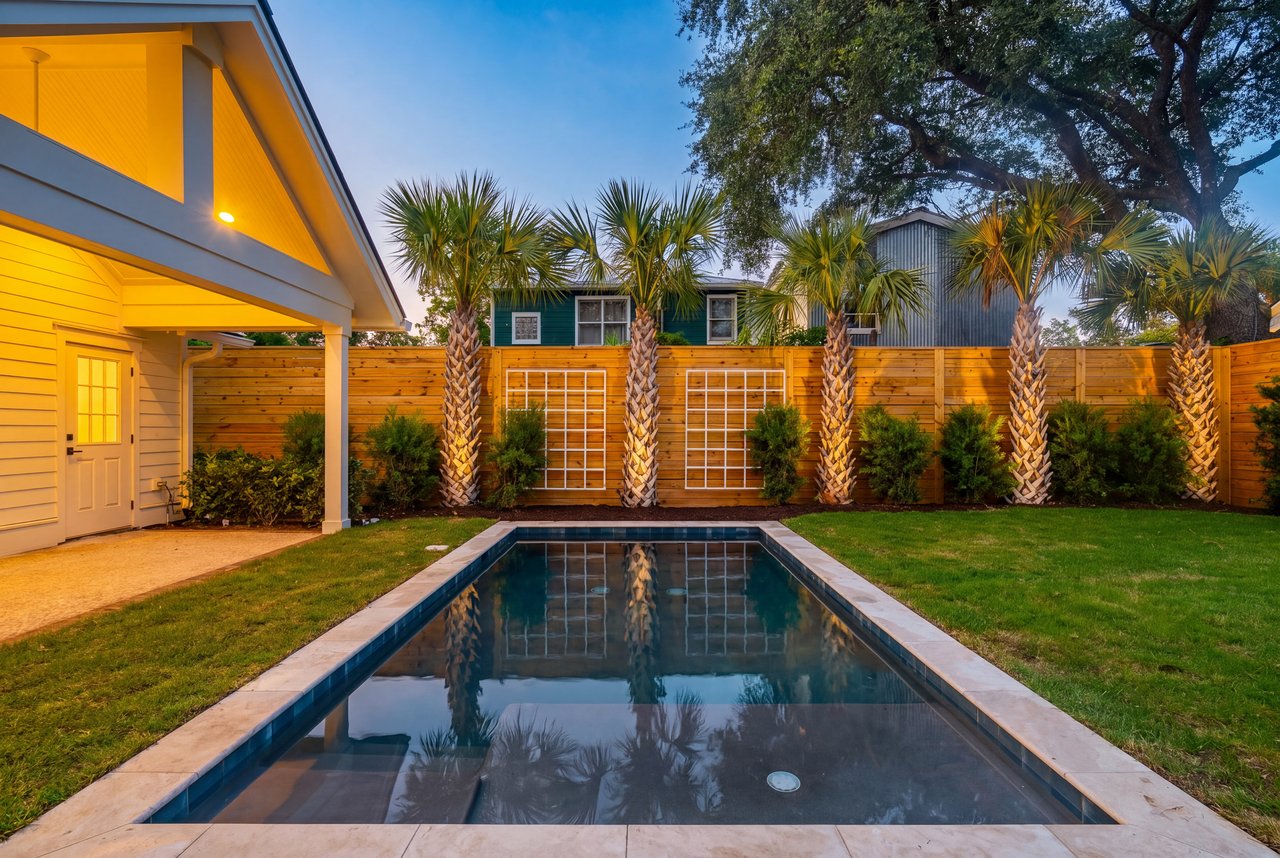
For buyers drawn to Old Mount Pleasant, 904 Randall Drive pairs new construction with the craftsmanship and warmth that make a home memorable. Built by Monarch Urban and designed by Coastal Creek Design, the five-bedroom home features European white oak floors, natural stone finishes, and a kitchen with Thermador appliances and a separate scullery. Primary suites on both floors offer flexibility, while covered porches and a saltwater pool create inviting spaces to gather outdoors. It is a property worth exploring for buyers evaluating a Charleston-area purchase and the rental strategy that might suit it. View 904 Randall Drive
For buyers considering a rental strategy, the next step is to evaluate permitted use and realistic operating numbers. Confirm rental rules and any required approvals with the Town of Mount Pleasant, and review potential income alongside insurance, property taxes, management fees, maintenance, and vacancy. Your CPA should assess which assets, if any, qualify based on your purchase and intended use. New construction and high-end finishes alone do not establish bonus-depreciation eligibility.
Contact our team for current availability, a private tour, and more details about 904 Randall Drive. We can help you gather property information to discuss with your CPA as you evaluate whether the home fits your investment plan. A thoughtful purchase starts with numbers that hold up beyond tax season.
General educational information based on guidance available September 14, 2026. This article is not individualized tax or legal advice. Consult your CPA and appropriate advisers before relying on a deduction or rental strategy.